The snowball starts with the smallest balance, so you close a debt quickly and stay motivated. The avalanche starts with the highest interest rate, so you pay the least interest in total.
Follow a payoff plan in Spendry
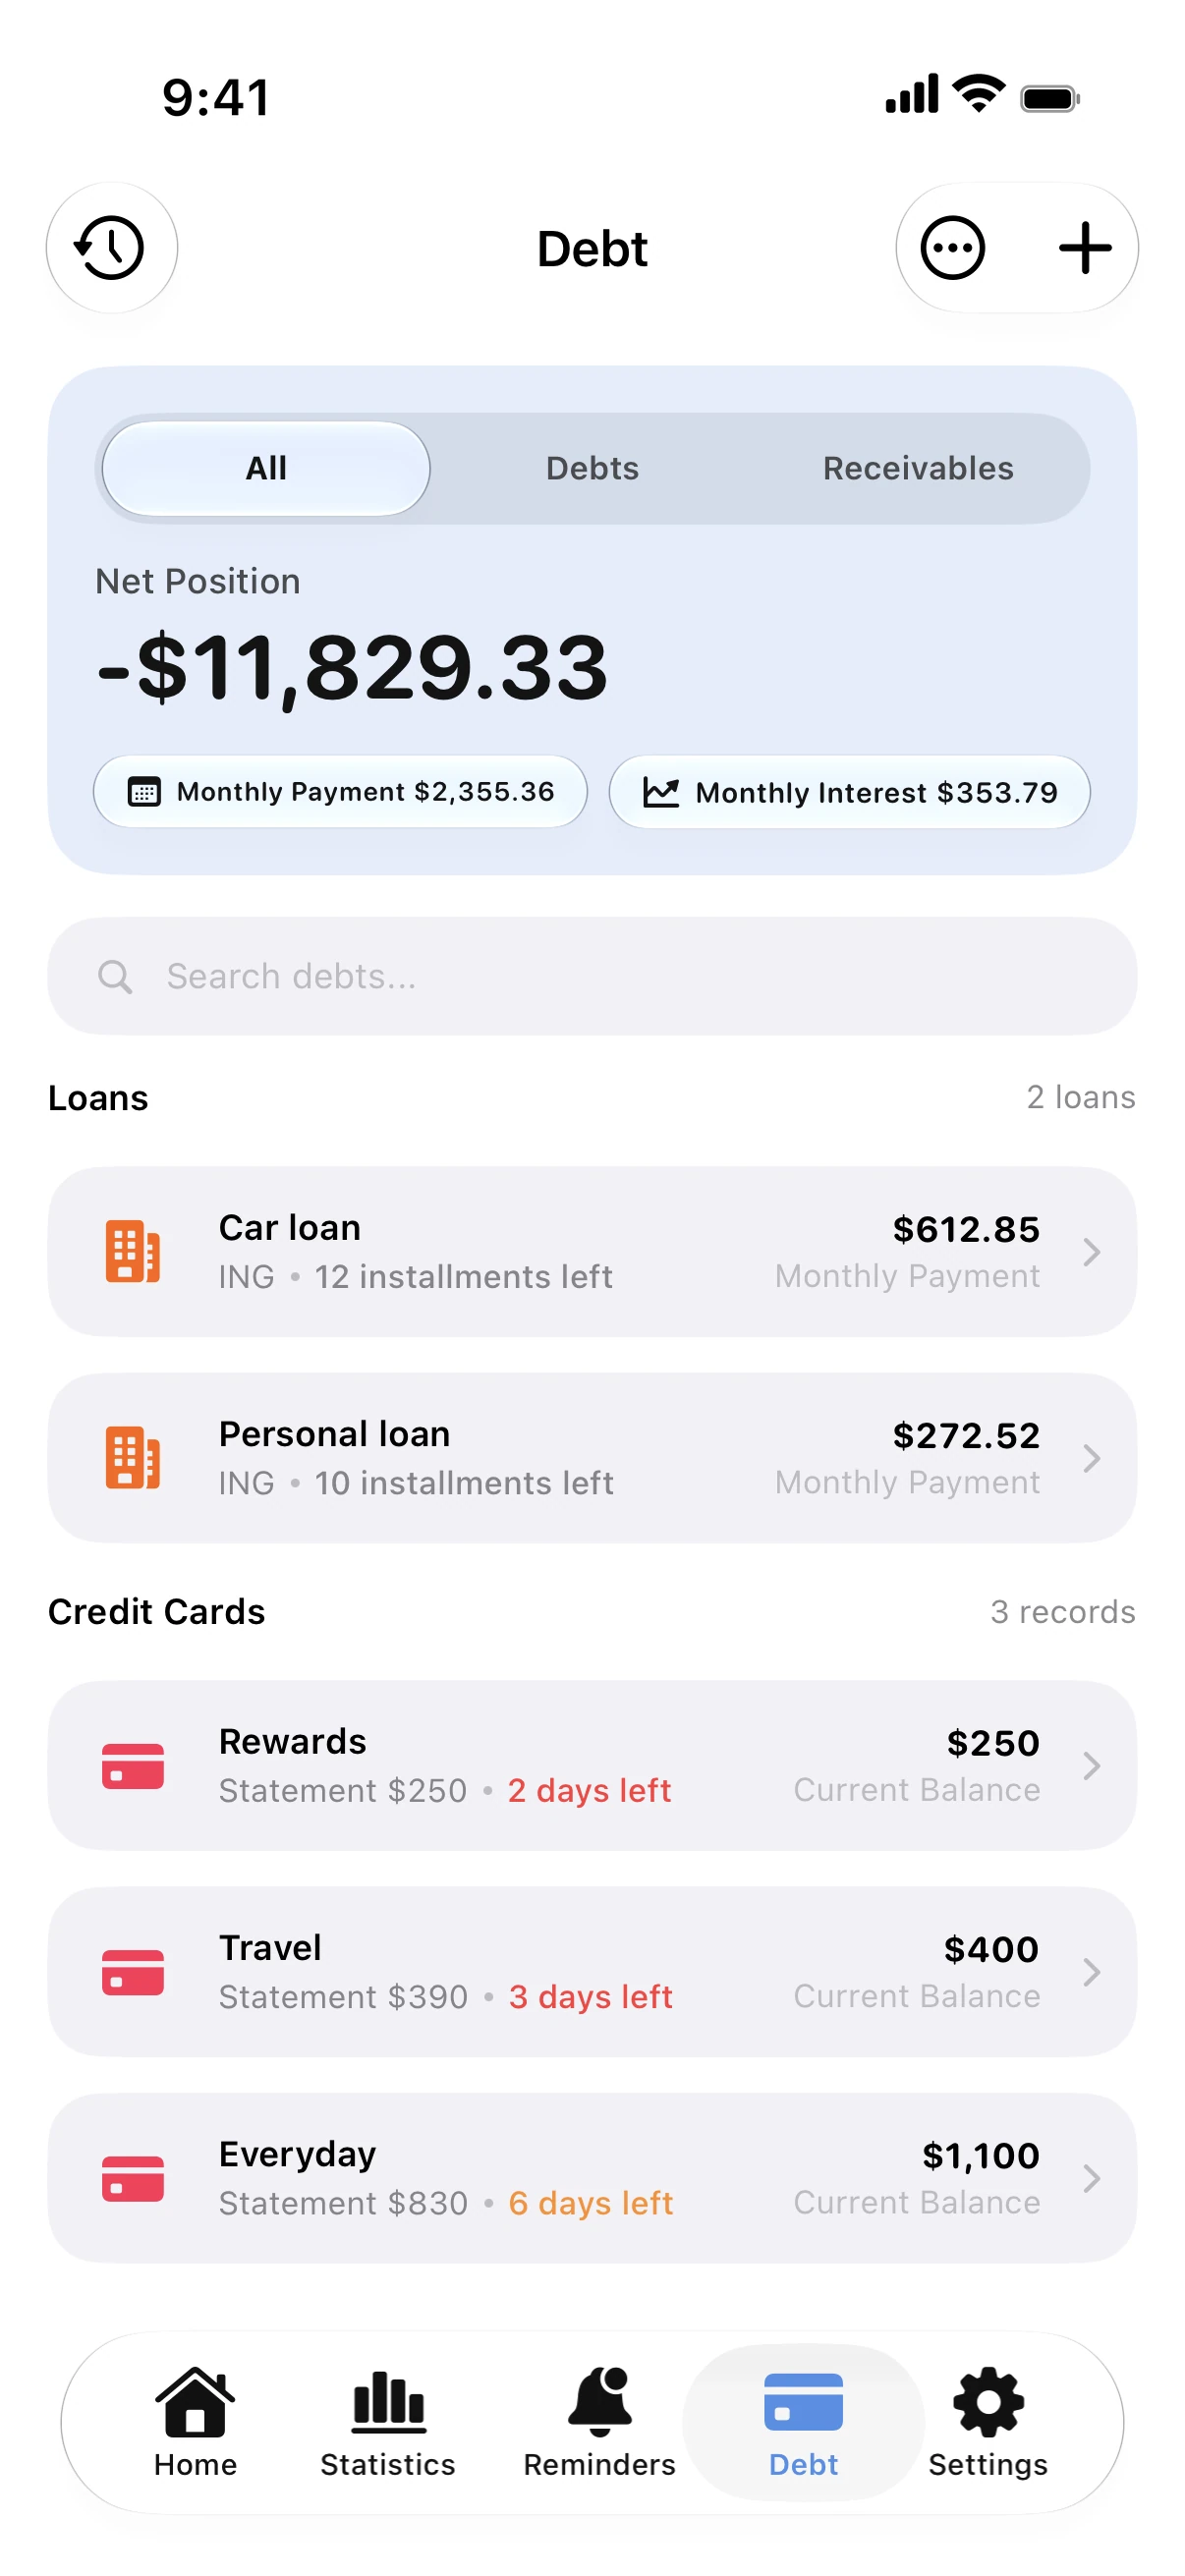
- Add each card, loan and installment with its balance, interest rate and minimum payment.
- Open Debts and choose the snowball or the avalanche method.
- Enter how much you can pay on top of the minimums each month.
- Spendry orders your debts and shows the month you'll be debt-free, with a reminder before every payment.
An example
Three debts: 1,200 at 24%, 4,000 at 18% and 9,000 at 9%, with 300 extra each month. The avalanche clears the 24% card first and pays the least interest. The snowball clears the 1,200 balance first, so one debt disappears within a few months. The finish lines are often only a month or two apart.
If the two dates are close, pick the method you will stick with. The best plan is the one you keep paying.
Debt payoff calculator
Free debt payoff calculator: compare the snowball and avalanche methods and see the month you'll be debt-free and the interest you'll pay. No sign-up.
Questions
Which method saves the most money?
The avalanche, because the most expensive debt shrinks first. How much it saves depends on how far apart your rates are.
Can I switch methods later?
Yes. Change the method in Spendry at any time and the plan and the debt-free date update right away.