
Debt payoff calculator
Enter your debts and what you can pay on top of the minimums each month. See your debt-free month and total interest with the snowball and avalanche methods side by side.
Sample debts; replace them with yours. Rates are treated as fixed, fees are not included.
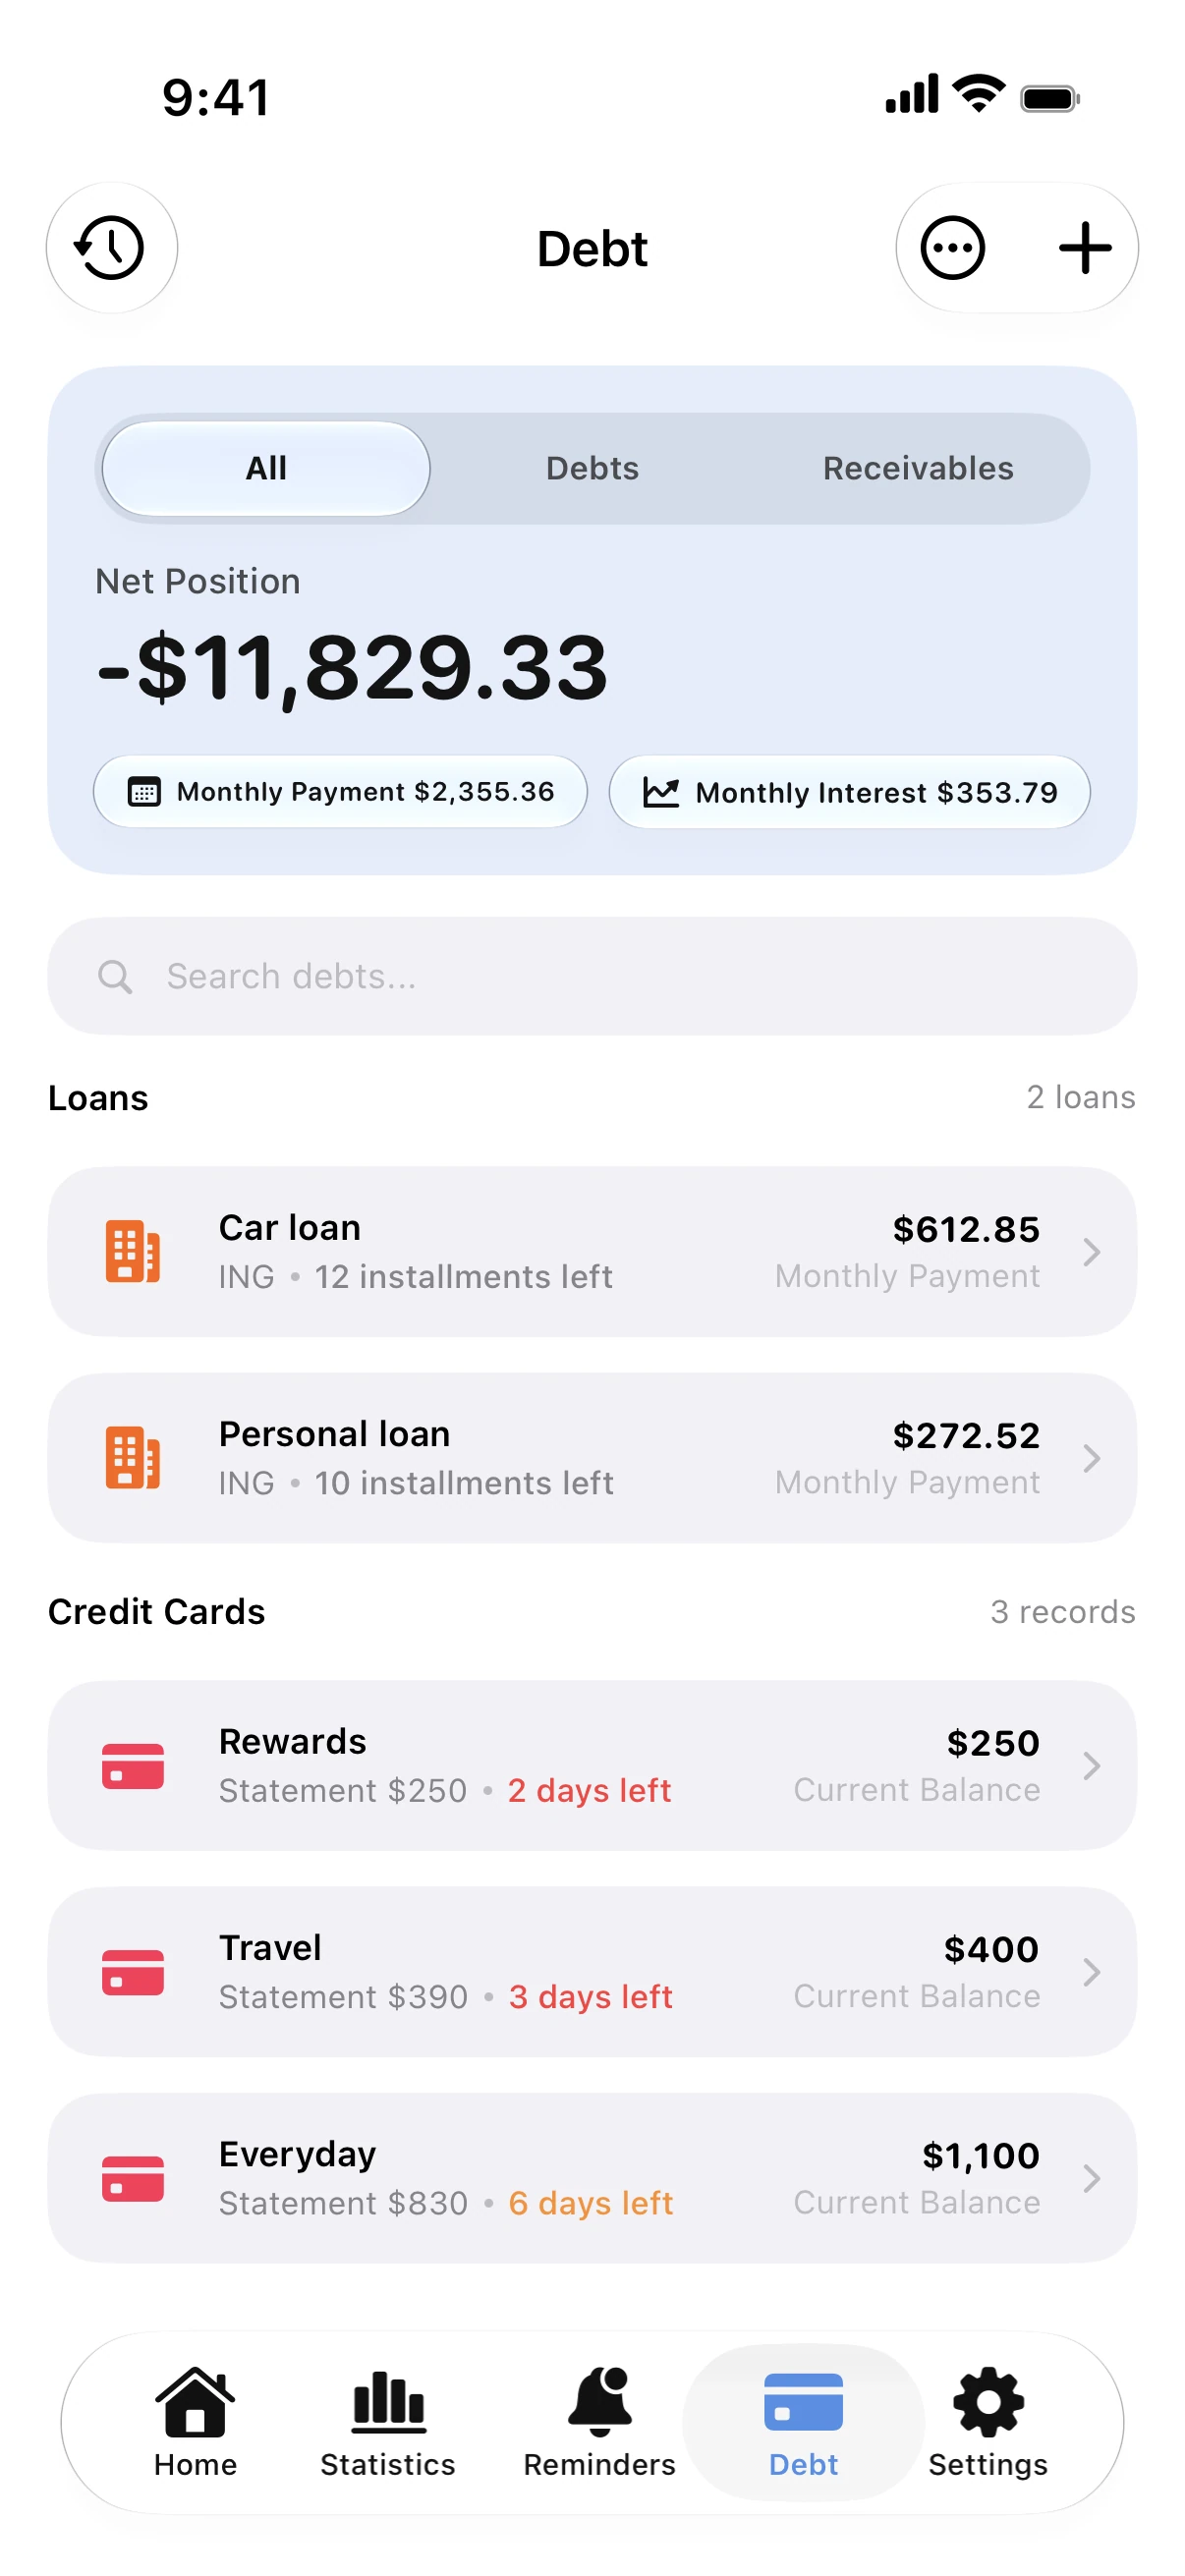

Move the slider and watch the month change. Spendry does this with your real debts and keeps the plan up to date.
Download on the App StoreSnowball or avalanche?
With the snowball method you pay off the smallest balance first. The first debt disappears quickly and its payment rolls into the next one, which keeps motivation high. With the avalanche method you pay off the highest interest rate first, which usually costs less interest overall, though the first payoff can take longer.
How the calculator works
Every month each debt gets its minimum payment. The extra goes to the next debt in line, and a cleared debt's payment rolls over to the next. Both methods use the same monthly budget, so the difference you see is only the order.
Keep the plan up to date
Balances change every month. Spendry tracks your cards, loans and bills, keeps your snowball or avalanche plan current and reminds you before each payment is due.
More guides
Debt snowball vs. avalanche: which one should you use?
The snowball pays the smallest balance first, the avalanche the highest rate. See how they differ, which saves more interest and how to follow either one.
How to find your debt-free date
Your debt-free date is the month your last debt is paid off. Here is how to work it out and how extra payments move it closer.
How to pay off credit card debt faster
Practical steps to pay off credit card debt faster: pay more than the minimum, aim extra money at the highest rate, never pay late and stop new balances.